A new expat's first UAE bank account should match their current identity documents, payroll needs and cash flow. Do not assume a digital account accepts an Emirates ID application receipt or that every resident account is zero balance. Ask the selected bank about the exact product before applying.
Before Emirates ID: establish which banking route is available
A visitor, an applicant waiting for residency documents and a resident with a completed Emirates ID are different onboarding cases. Ask whether the bank offers an appropriate non-resident or temporary route, which documents it accepts, and whether you can receive salary, obtain a debit card or write cheques. Do not treat a savings account as a substitute for a full current account without checking those functions.
Prepare a passport, visa or residency evidence, address details and any employment or source-of-funds documents requested. Send them only through the bank's official process. A promise from a recruitment agent or a social-media contact is not a bank eligibility decision.
After Emirates ID: compare the actual account requirements
ADCB's resident current-account page identifies resident eligibility and salary requirements, alongside relationship-balance fees. Other products have their own rules. Read the key facts statement and schedule for the specific account, not only the headline describing the banking app.
| Which identity documents are accepted now? | An incomplete application can delay access to money |
| What counts as salary? | A transfer from your own account may not qualify |
| How is the balance measured? | Average balances and day-end balances can differ |
| Is a cheque book available? | Your tenancy payment plan may require it |
| What is charged for remittances? | Transfer fees and the exchange rate both matter |
Set up UAE PASS without assuming universal service access
Use the official UAE PASS registration route and complete the identity verification available for your documents. Confirm the bank supports that onboarding method. UAE PASS is an identity tool, not a bank account, a residency permit or a credit approval.
Keep your own mobile number and email attached to the account. Verify the IBAN from the bank's app or official documents before giving it to HR; never copy a payment instruction supplied only by an unverified intermediary.
Compare account costs before moving your salary
Work through the UAE bank accounts directory and salary transfer tracker. Compare the first-year cash offer with recurring package fees, required balances, the number of salary credits and any reversal clause. A larger bonus can be a poor fit if it locks up cash you need for rent.
For an illustration, a hypothetical AED 500 bonus with AED 25 monthly fees leaves AED 200 after twelve months, before remittance costs. Those are example inputs, not a quoted account offer. A fee waiver you cannot maintain should not be treated as zero cost.
Plan rent, utility deposits and the first salary gap
List tenancy deposits, rent instalments, utility activation, transport and school registration by due date. Keep an accessible reserve rather than putting every dirham into a balance requirement or deposit-backed card. Ask HR when the first salary will arrive and whether a partial first month changes an offer tier.
The first 90 days checklist records completed tasks on your device. It is a planning sequence; bank and government processing times are not promised.
Choose a credit card after repayment is comfortable
An account relationship does not automatically qualify you for a card. Use the personal selector to compare published salary rules and your spending, then confirm employer, service-length and bureau requirements with the bank. Start with the cashback category only when you expect to repay the full statement.
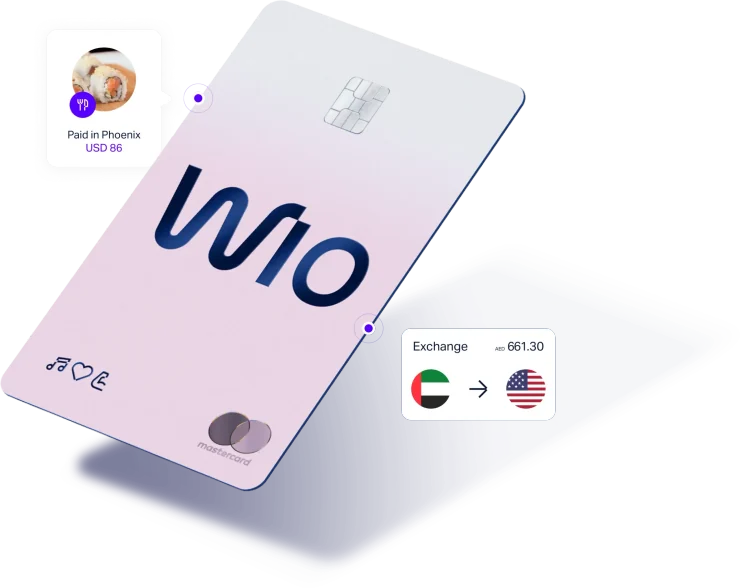
Wio Credit
- Salary minimum
- AED 7,000
- Annual fee
- AED 0
- First-year estimate
- AED 1,632
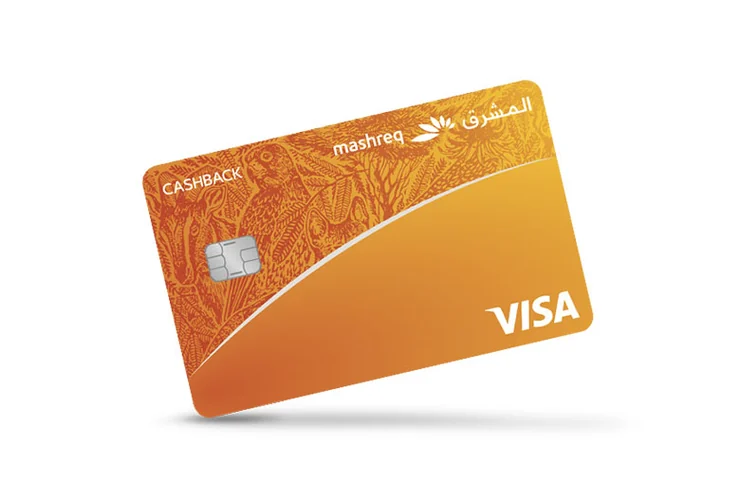
Mashreq Cashback Credit Card
- Salary minimum
- AED 5,000
- Annual fee
- AED 0
- First-year estimate
- AED 2,063
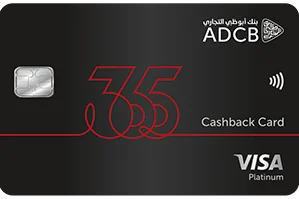
ADCB 365 Cashback Credit Card
- Salary minimum
- AED 5,000
- Annual fee
- AED 383.25
- First-year estimate
- AED 3,305
Related card reviews and fee math
Read these comparison records alongside the article; inclusion does not establish personal eligibility or approval.
What changed in this edition
First published 22 October 2026 with official source links, worked illustrations and explicit unverified-data limits. Embedded bank records retain their own source-check dates.
Explore the matching UAE card category · Calculate rewards for your own spending
Frequently asked questions
Can I open a UAE digital account before my Emirates ID arrives?
Acceptance depends on the bank and exact account. Ask which temporary or non-resident route exists and whether the application receipt is accepted; do not assume it is sufficient.
Does a salary transfer guarantee a credit card?
No. Card approval has separate identity, income, employer, affordability and credit-assessment requirements.
Sources & review
Article updated 22 Oct 2026. Embedded product records show their own source-check dates. Conditions can change after review.